
August 2026 Monthly Market Insights
Data and opinions as of July 31, 2026
Markets widen their field of vision
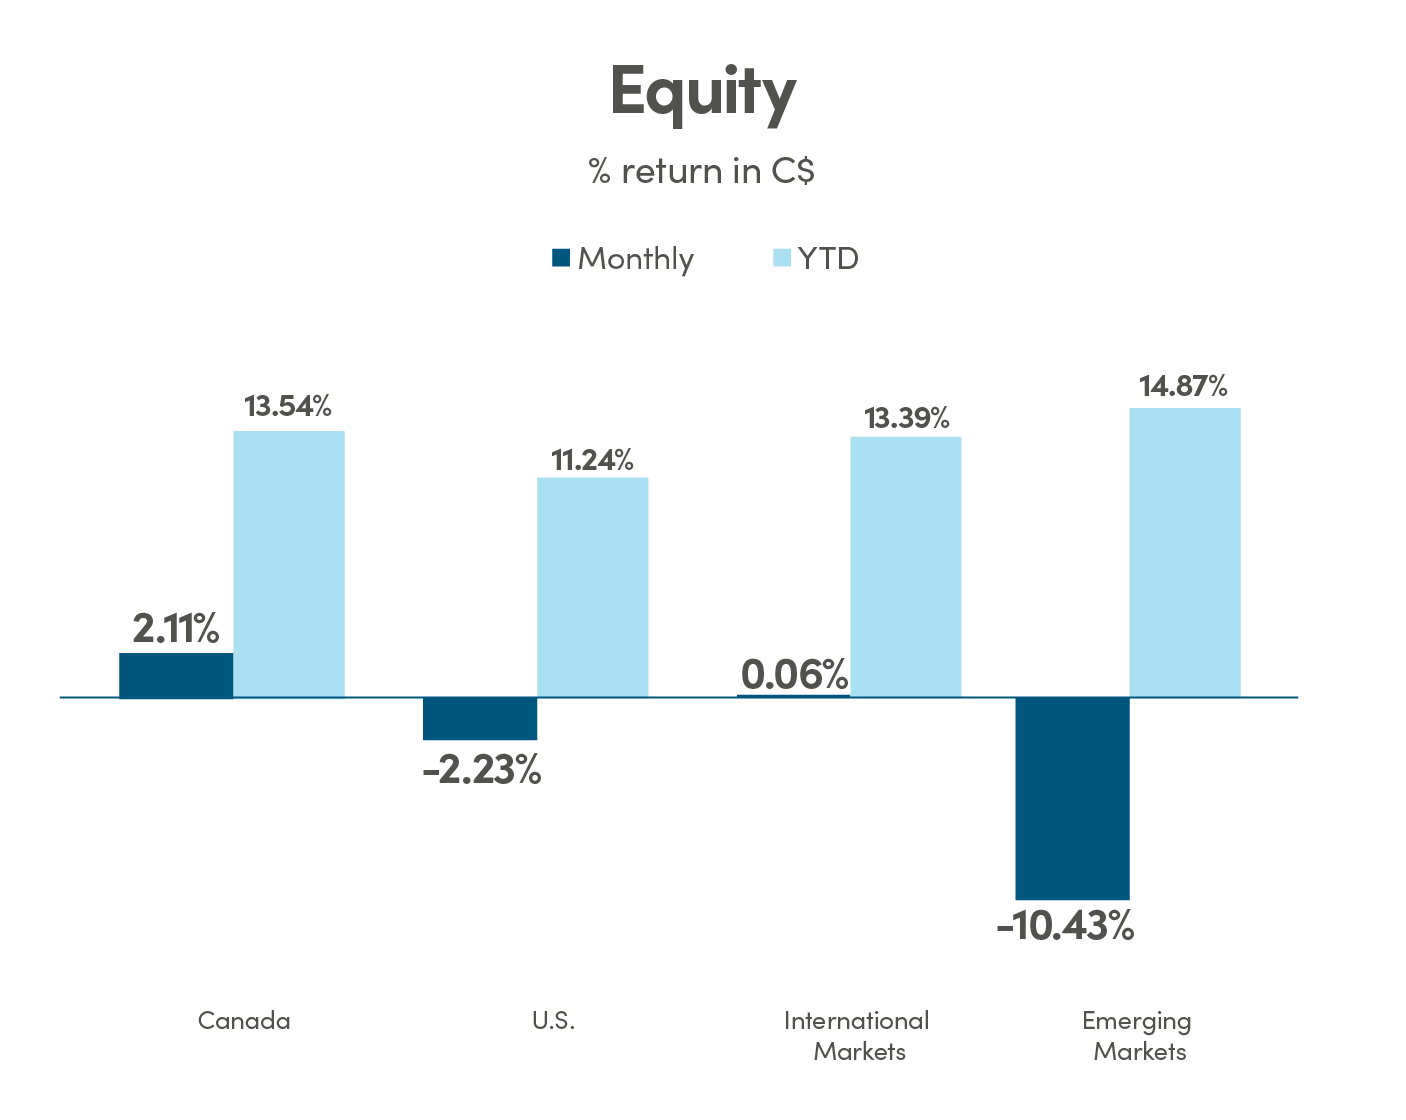
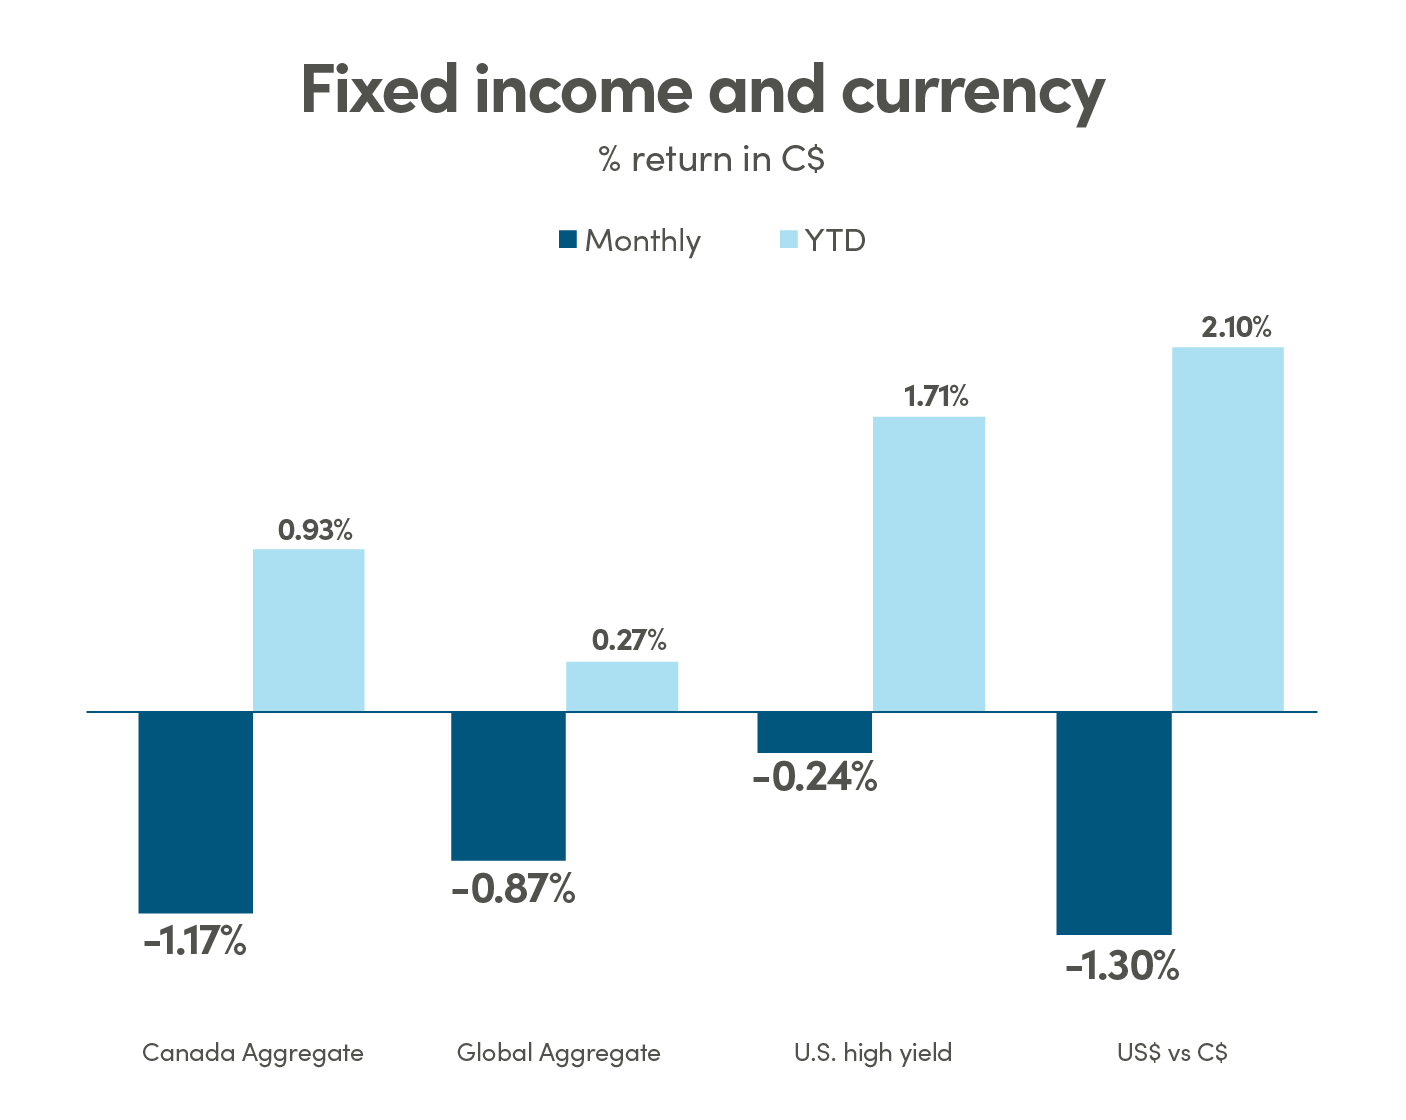
July forced investors to look beyond the most obvious signals. The Federal Reserve held its policy rate steady, but the reaction in longer-term bond yields showed that financial conditions can change even when the overnight rate does not. Strong technology earnings confirmed that AI demand remains powerful, but rising capital requirements shifted attention toward cash-flow generation and the eventual return on that spending. At the same time, improving performance from the equal-weighted S&P 500 suggested that the opportunity set is expanding beyond the largest technology companies. The market is increasingly organizing around two broad themes, AI and not AI, while also finding underappreciated businesses that support the buildout from outside the mega-cap technology complex.
NEI Perspectives
Fed holds as the yield curve steepens: Three policymakers voted for a rate increase, while higher long-term yields pressured growth stocks and longer-duration bonds. Bottom line: If the equity market was not already watching the bond market, it is now.
AI earnings meet the cash-flow test: Alphabet’s strong results were overshadowed by heavy capital spending, while disruption concerns continued to weigh on software companies. Bottom line: Investors increasingly want proof that AI investment can generate durable returns.
The market broadens beyond mega-cap tech: The equal-weighted S&P 500 is making up ground as investors find underappreciated AI picks-and-shovels and opportunities outside the dominant theme. Bottom line: The diversification trade remains in play.
- NEI Asset Allocation Team
Source: Bloomberg.
Fed stays on hold as the inflation debate moves into the bond market
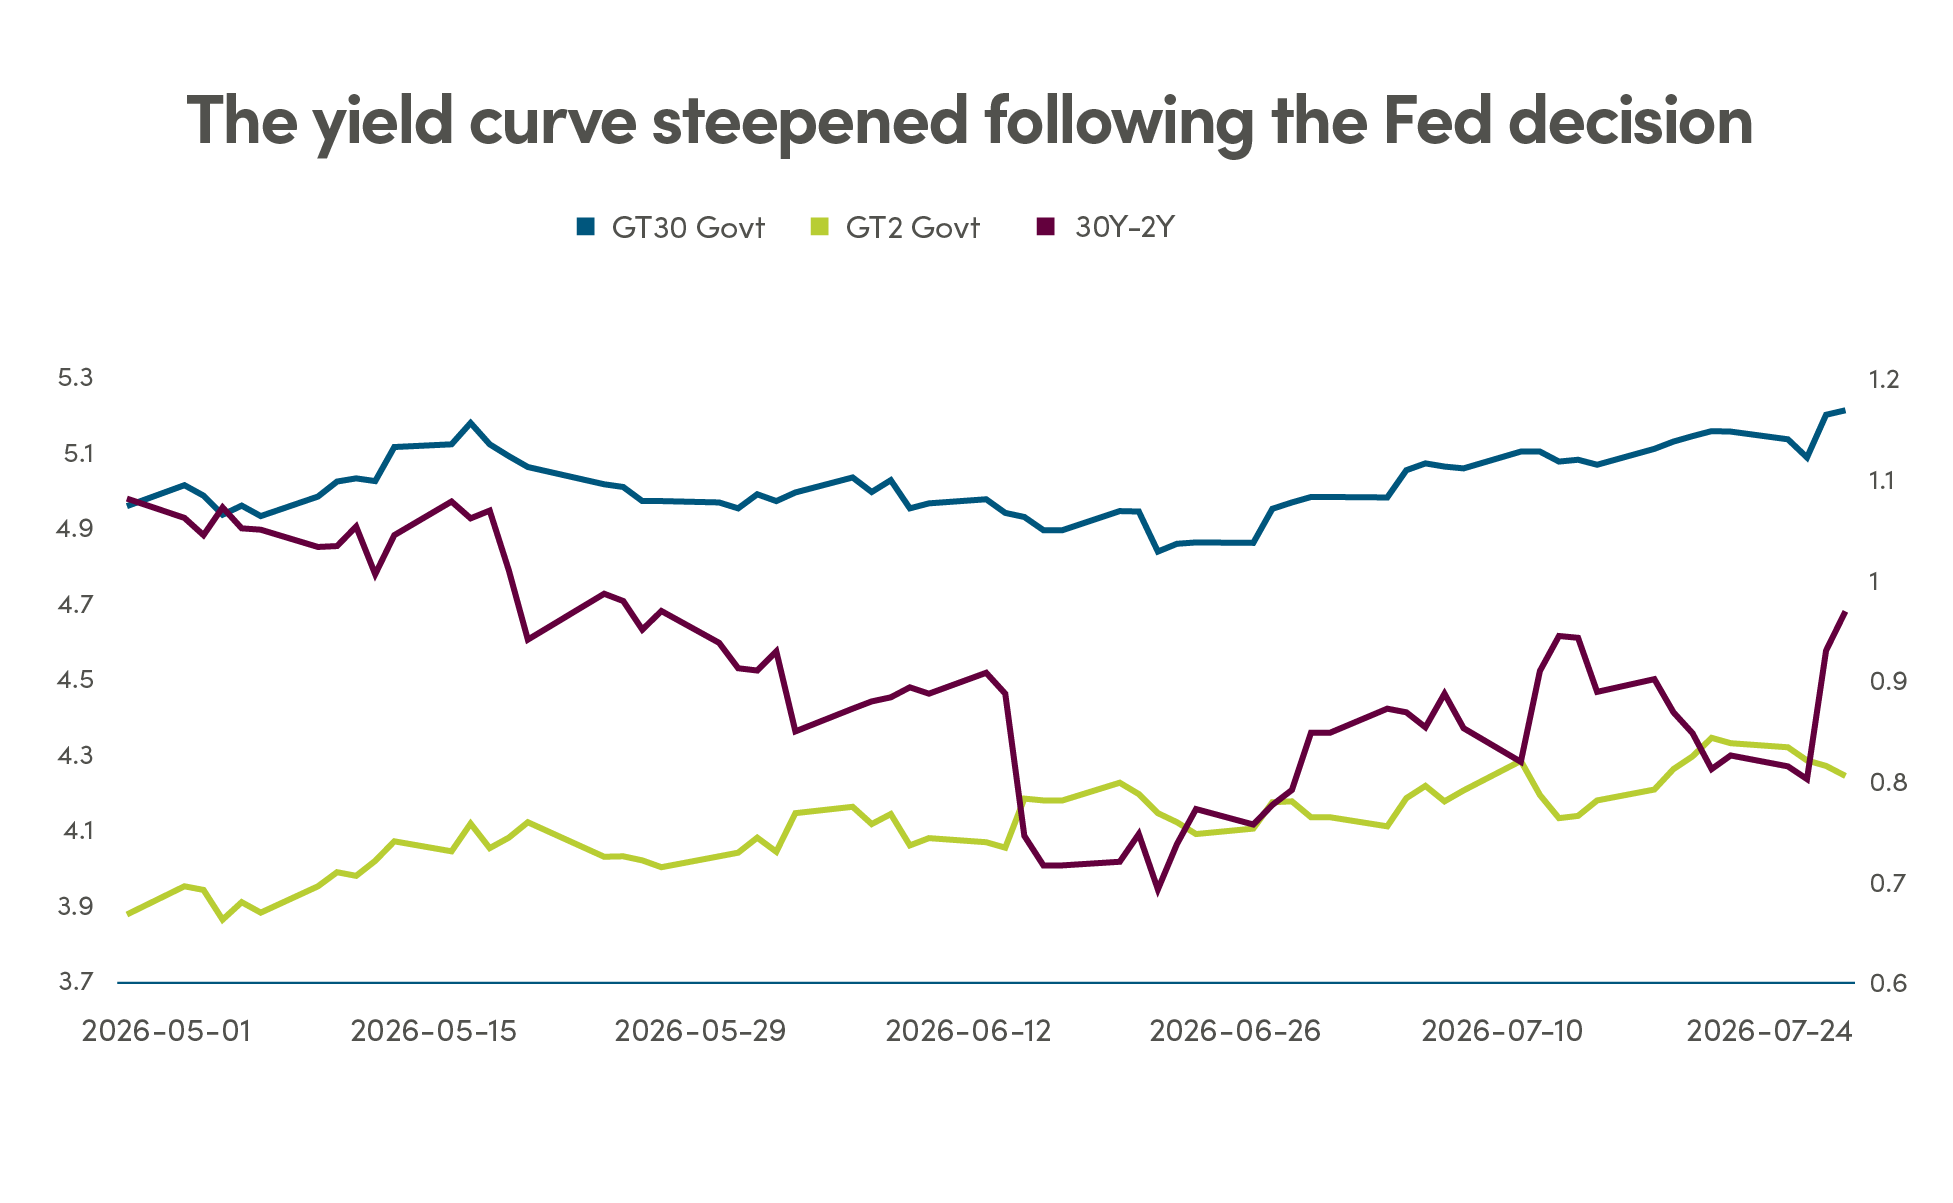
The Federal Reserve held its policy rate at 3.50% to 3.75% in July, but the 9–3 decision revealed a meaningful divide within the committee. Three policymakers preferred a 25-basis-point increase, while the majority opted to remain on hold. Chair Warsh reinforced the Fed’s commitment to its 2% inflation target but offered limited forward guidance, leaving incoming economic data and market prices to play a larger role in shaping rate expectations.
The bond market delivered a clear response. The yield curve steepened, with upward pressure further out the maturity spectrum signalling continued concern around inflation, economic resilience and the risk that rates stay elevated. If the equity market was not already watching the bond market, it is now. Higher long-term yields increase discount rates and create a shared headwind for long-duration assets, including growth equities and longer-maturity bonds. The Fed may have stayed put, but financial conditions did not.
Source: Bloomberg.
Bottom line: An unchanged policy rate does not mean unchanged financial conditions. With longer-term yields under pressure, the bond market may now matter more for portfolios than the Fed’s latest rate decision alone.
AI earnings meet the cash-flow test
Alphabet delivered a resounding quarter, with revenue up 24%, Google Cloud revenue up 82%, and operating margins expanding to 34%. But investors focused on the cost of that growth. Quarterly capital expenditures reached US$44.9 billion, exceeding US$39.1 billion in operating cash flow and pushing free cash flow into negative territory. While the results reinforced that AI demand is real, the bar for proving that today’s infrastructure spending can generate attractive returns has also raised.
The pressure is creating a sharp divide within technology. Semiconductor and memory stocks remain major beneficiaries of the AI infrastructure buildout, despite taking a breather in July after strong year-to-date gains. Software companies face the opposite question: whether AI will enhance their products or replace parts of their traditional subscription models. As AI platforms move further into the application layer, investors are becoming increasingly selective about who captures the economics of the buildout and who risks being disrupted.
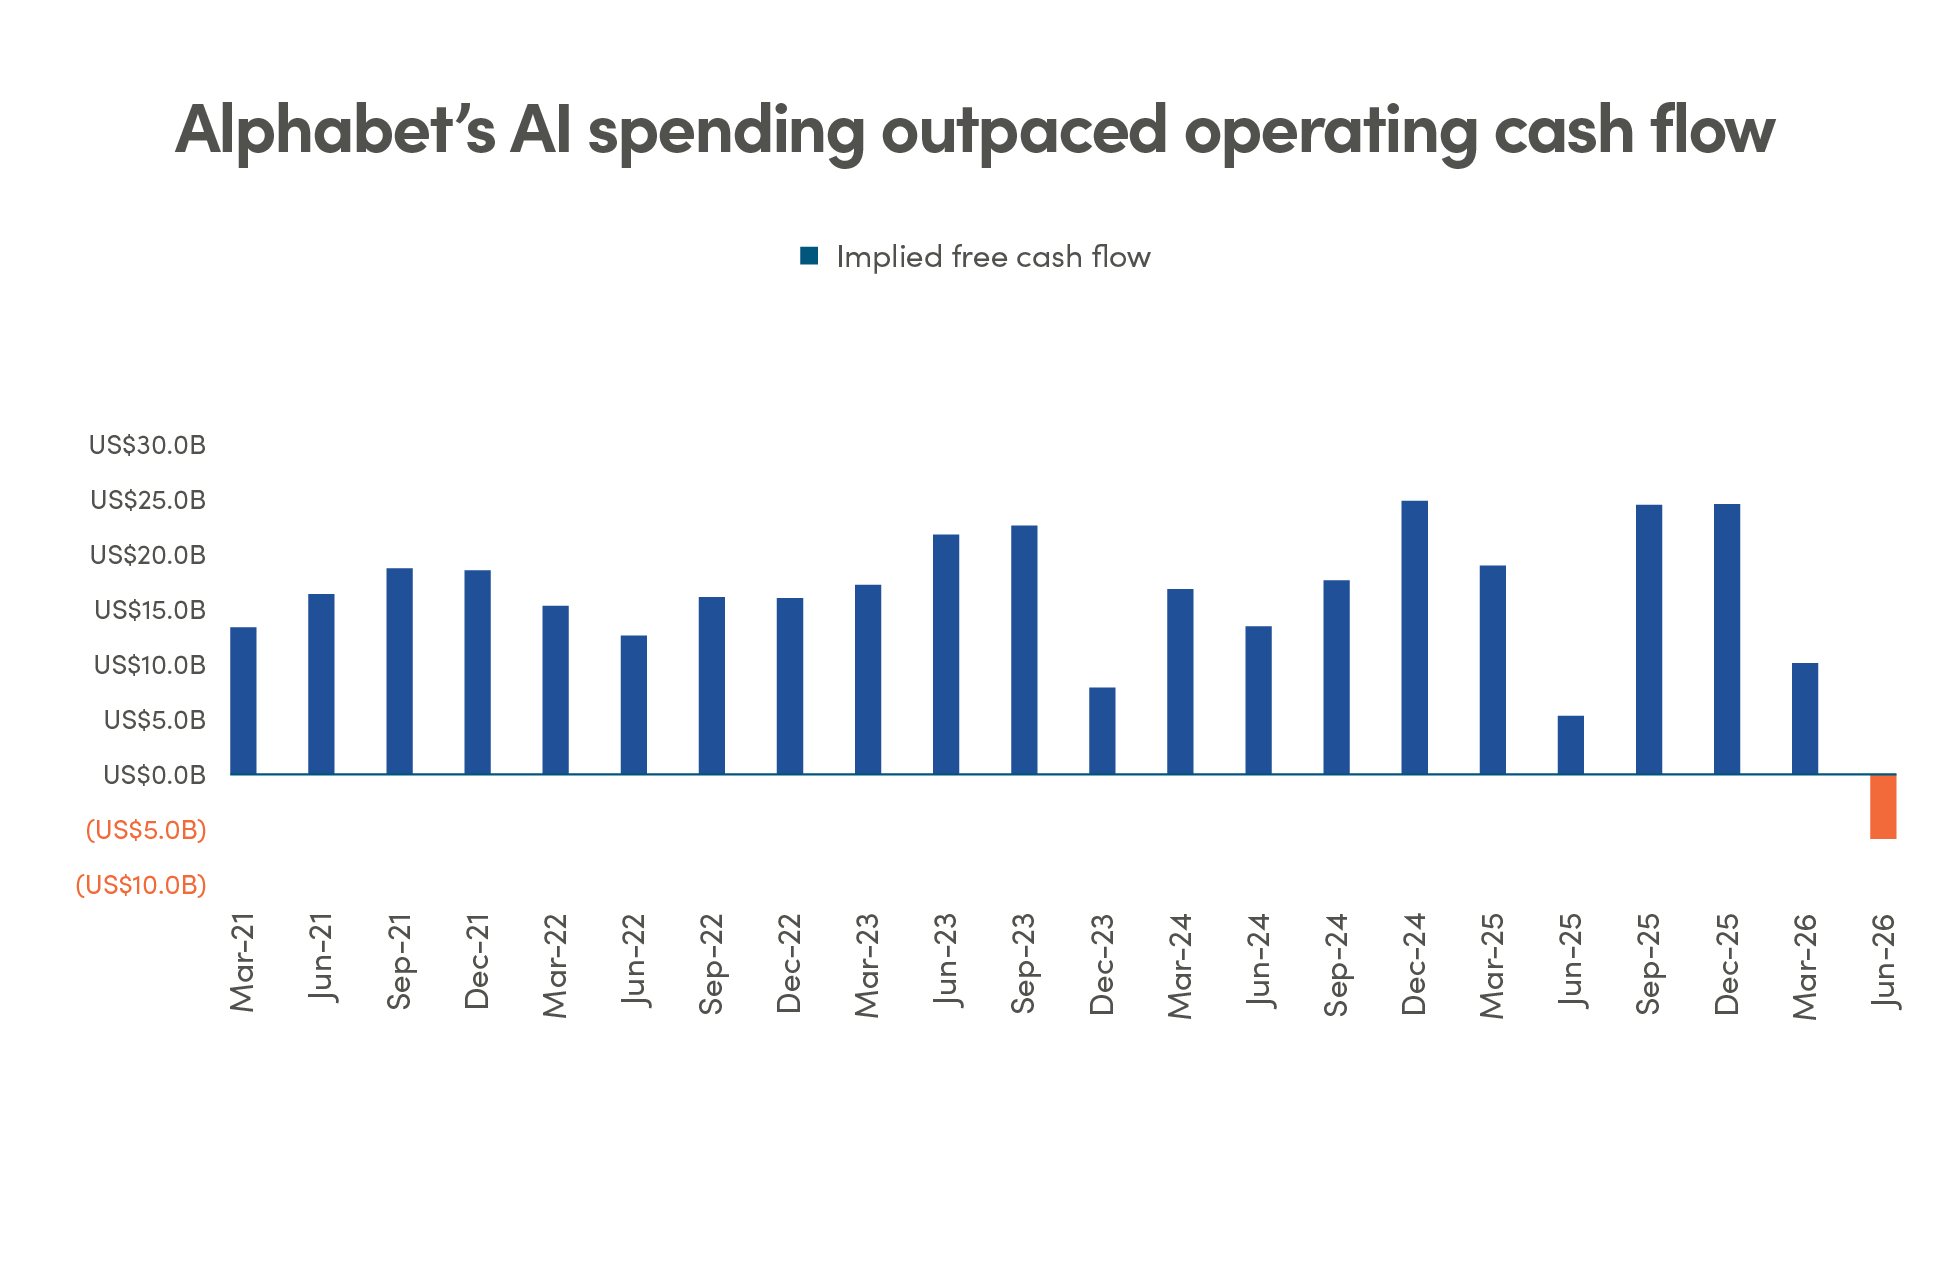
Source: Bloomberg.
Bottom line: The AI theme remains powerful, but the standard for success is rising. Investors increasingly want proof that AI spending can translate into durable free cash flow, not just faster revenue growth.
The market broadens into AI, and everything else
The equity market is increasingly loading up on two broad themes: AI and not AI. Mega-cap technology remains at the centre of the AI trade, but the diversification trade is still in play. Over the past three months, the equal weighted S&P 500 has begun making up ground against the capitalization-weighted index, suggesting the rally is reaching beyond its largest constituents. Because the equal-weighted index assigns the same weight to every S&P 500 company, it increases exposure to the smaller companies within the large-cap universe and provides a clearer view of how the average stock is performing.
Importantly, broadening does not necessarily mean rotating away from AI. Many less prominent industrial, electrical-equipment, power-management and infrastructure companies provide the picks and shovels supporting the AI buildout. Others are genuine diversifiers, with earnings driven by consumer demand, domestic activity or company-specific fundamentals rather than AI investment. The opportunity set is widening both around the buildout and beyond it.
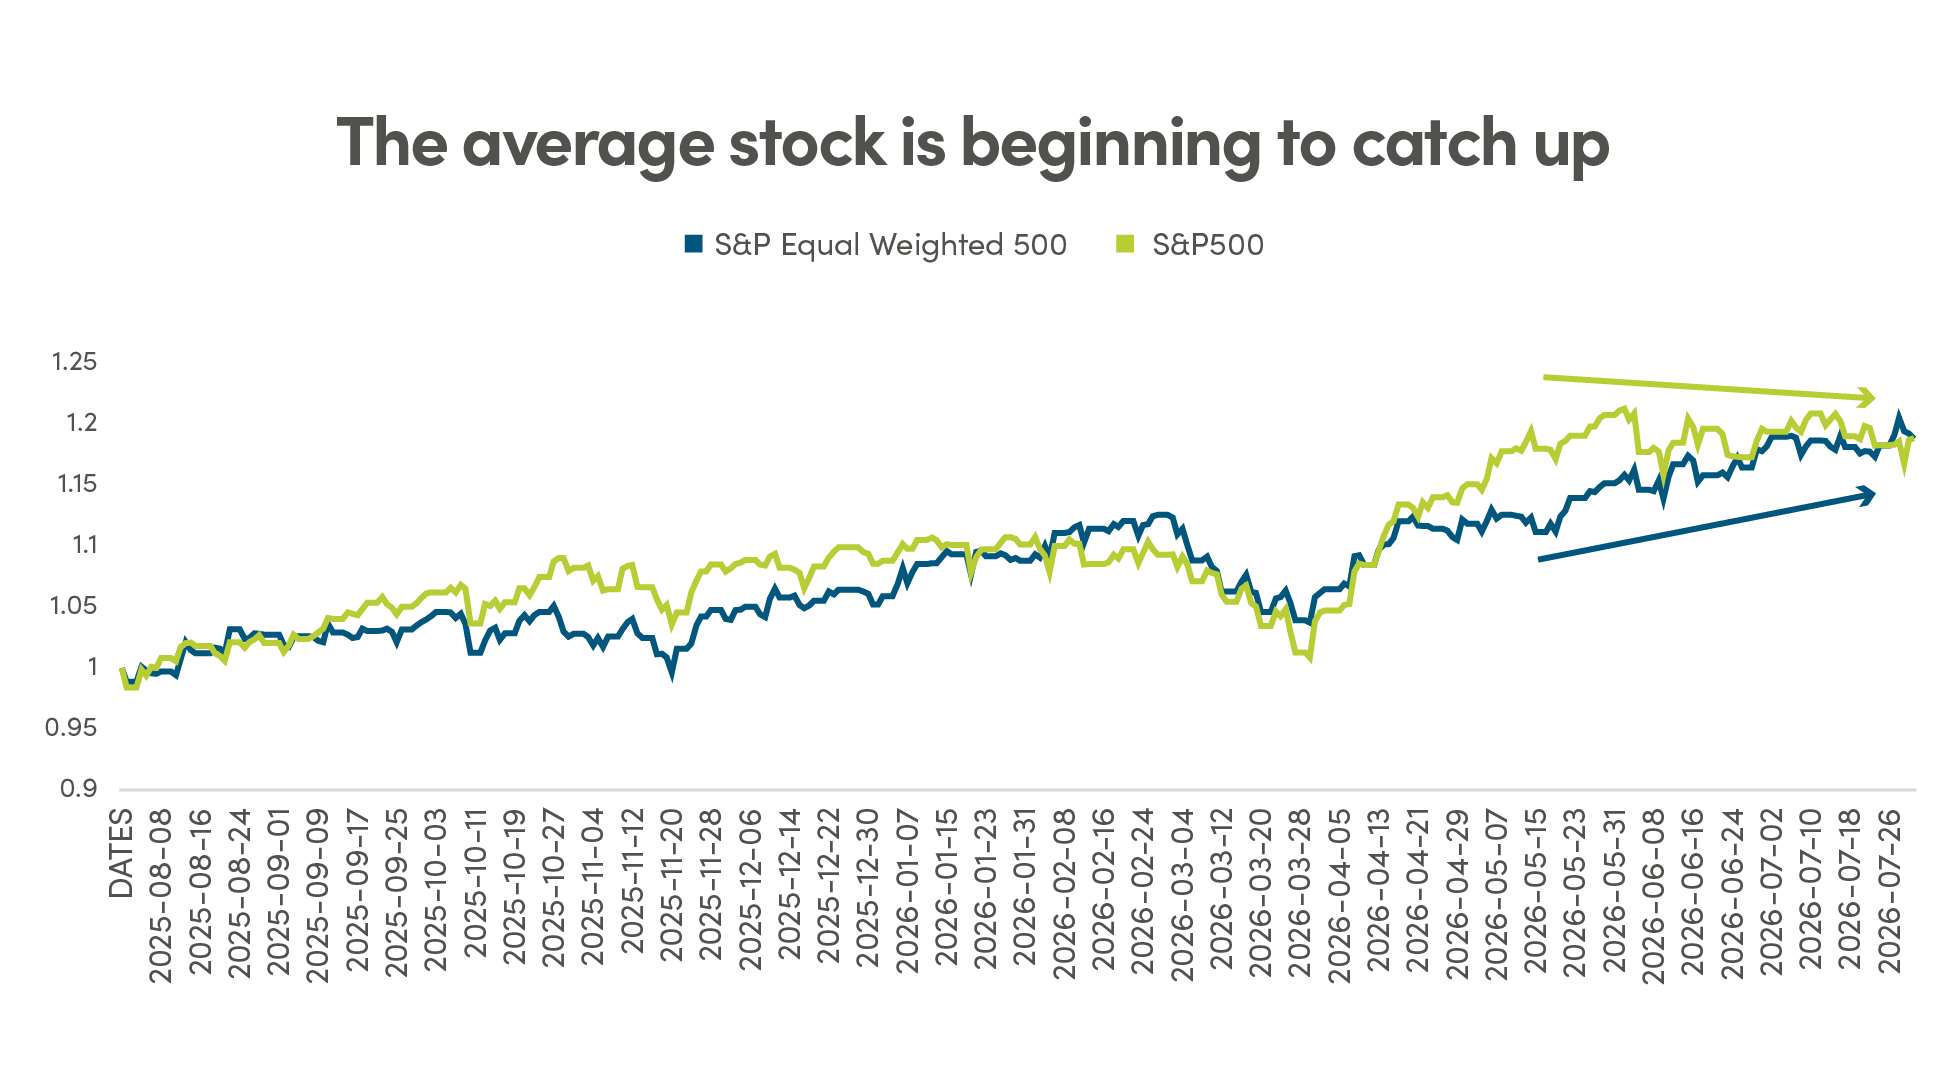
Source: N/A
Bottom line: Market concentration remains elevated, but participation is broadening. Equal weighting can capture underappreciated beneficiaries of the AI buildout while reducing reliance on the handful of mega-cap companies dominating the index.
Data and opinions as of July 31, 2026.
Aviso Wealth Inc. (“Aviso”) is the parent company of Aviso Financial Inc. (“AFI”) and Northwest & Ethical Investments L.P. (“NEI”). Aviso and Aviso Wealth are registered trademarks owned by Aviso Wealth Inc. NEI Investments is a registered trademark of NEI. Any use by AFI or NEI of an Aviso trade name or trademark is made with the consent and/or license of Aviso Wealth Inc. Aviso is a wholly-owned subsidiary of Aviso Wealth LP, which in turn is owned 50% by Desjardins Financial Holding Inc. and 50% by a limited partnership owned by the five Provincial Credit Union Centrals and The CUMIS Group Limited.
This material is for informational and educational purposes and it is not intended to provide specific advice including, without limitation, investment, financial, tax or similar matters. This document is published by AFI and unless indicated otherwise, all views expressed in this document are those of AFI. The views expressed herein are subject to change without notice as markets change over time. Views expressed regarding a particular industry or market sector should not be considered an indication of trading intent of any funds managed by NEI Investments. Forward-looking statements are not guaranteed of future performance and risks and uncertainties often cause actual results to differ materially from forward-looking information or expectations. Do not place undue reliance on forward-looking information. Mutual funds and other securities are offered through Aviso Financial Inc. Commissions, trailing commissions, management fees and expenses all may be associated with mutual fund investments. Please read the prospectus before investing. Unless otherwise stated, mutual fund securities and cash balances are not insured nor guaranteed, their values change frequently and past performance may not be repeated.
The MSCI information may only be used for your internal use, may not be reproduced or re-disseminated in any form and may not be used as a basis for or a component of any financial instruments or products or indices. None of the MSCI information is intended to constitute investment advice or a recommendation to make (or refrain from making) any kind of investment decision and may not be relied on as such. Historical data and analysis should not be taken as an indication or guarantee of any future performance, analysis, forecast or prediction. The MSCI information is provided on an “as is” basis and the user of this information assumes the entire risk of any use made of this information. MSCI, each of its affiliates and each other person involved in or related to computing, computing or creating any MSCI information (collectively, the “MSCI Parties”) expressly disclaims all warranties (including, without limitation, any warranties of originality, accuracy, completeness, timeliness, non-infringement, merchantability and fitness for a particular purpose) with respect to this information. Without limiting any of the foregoing, in no event shall any MSCI Party have any liability for any direct, indirect, special, incidental, punitive, consequential (including, without limitation, lost profits) or any other damages.
©2026 Morningstar. All Rights Reserved. The information contained herein: (1) is proprietary to Morningstar Research Services LLC, Morningstar, Inc. and/or their content providers; (2) may not be copied or distributed; and (3) is not warranted to be accurate, complete or timely. Neither Morningstar Research Services, Morningstar nor their content providers are responsible for any damages or losses arising from any use of this information. Access to or use of the information contained herein does not establish an advisory or fiduciary relationship with Morningstar Research Services, Morningstar, Inc. or their content providers. Past performance is no guarantee of future results.