
July 2026 Monthly Market Insights
Data and opinions as of June 30, 2026
A more nuanced macro regime
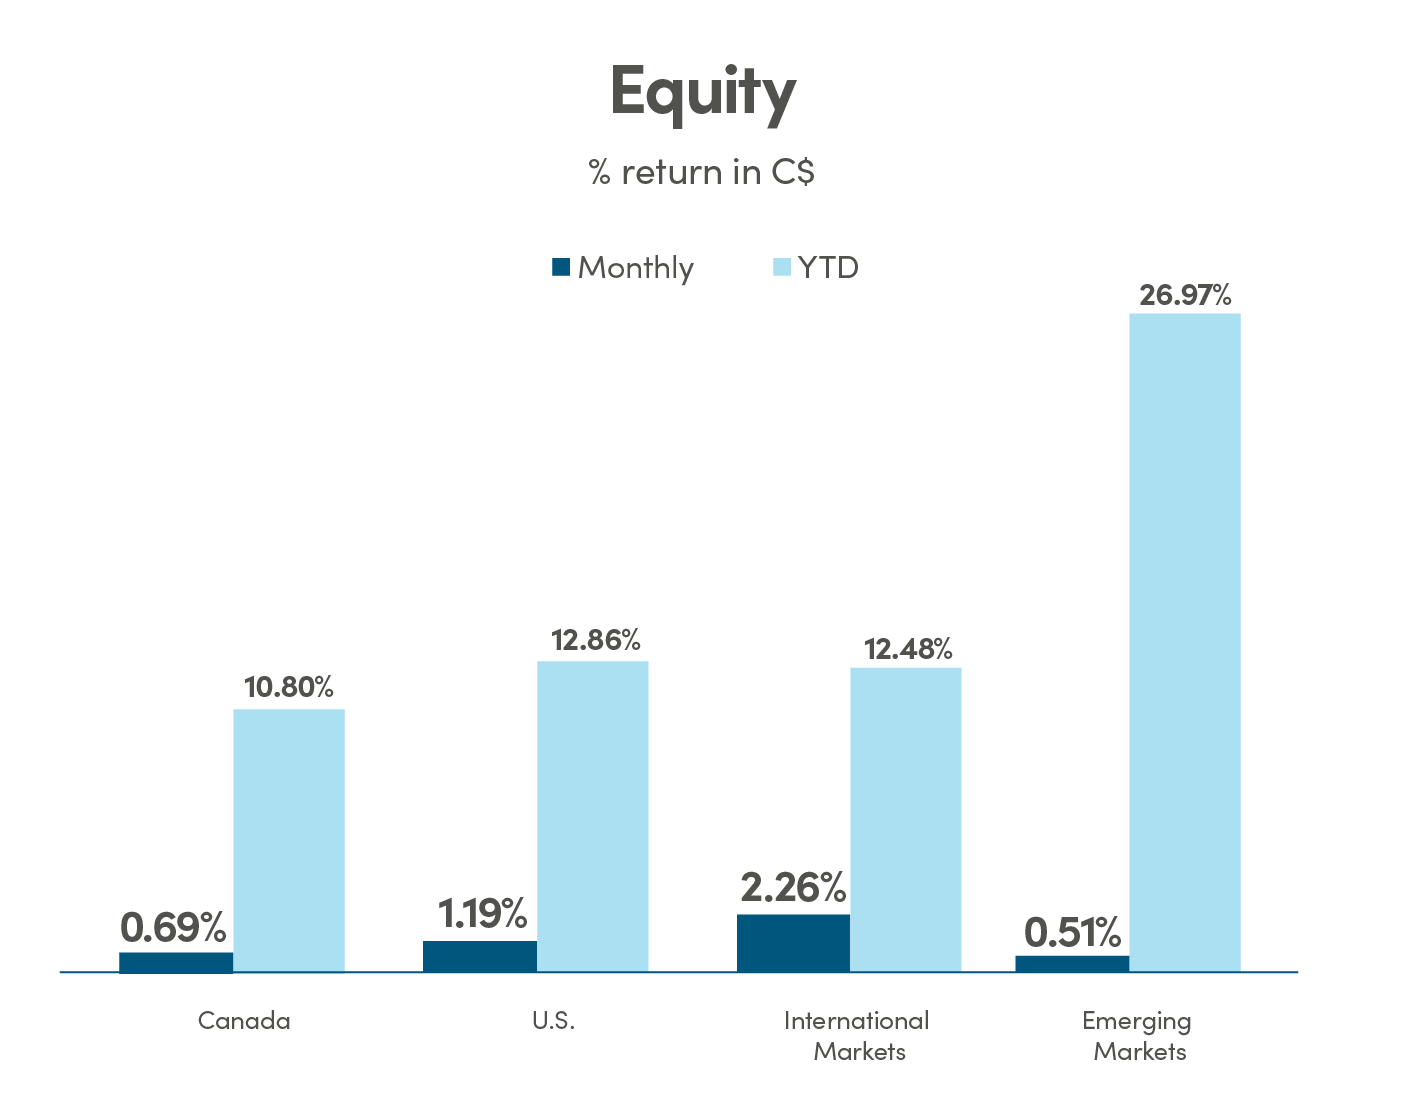
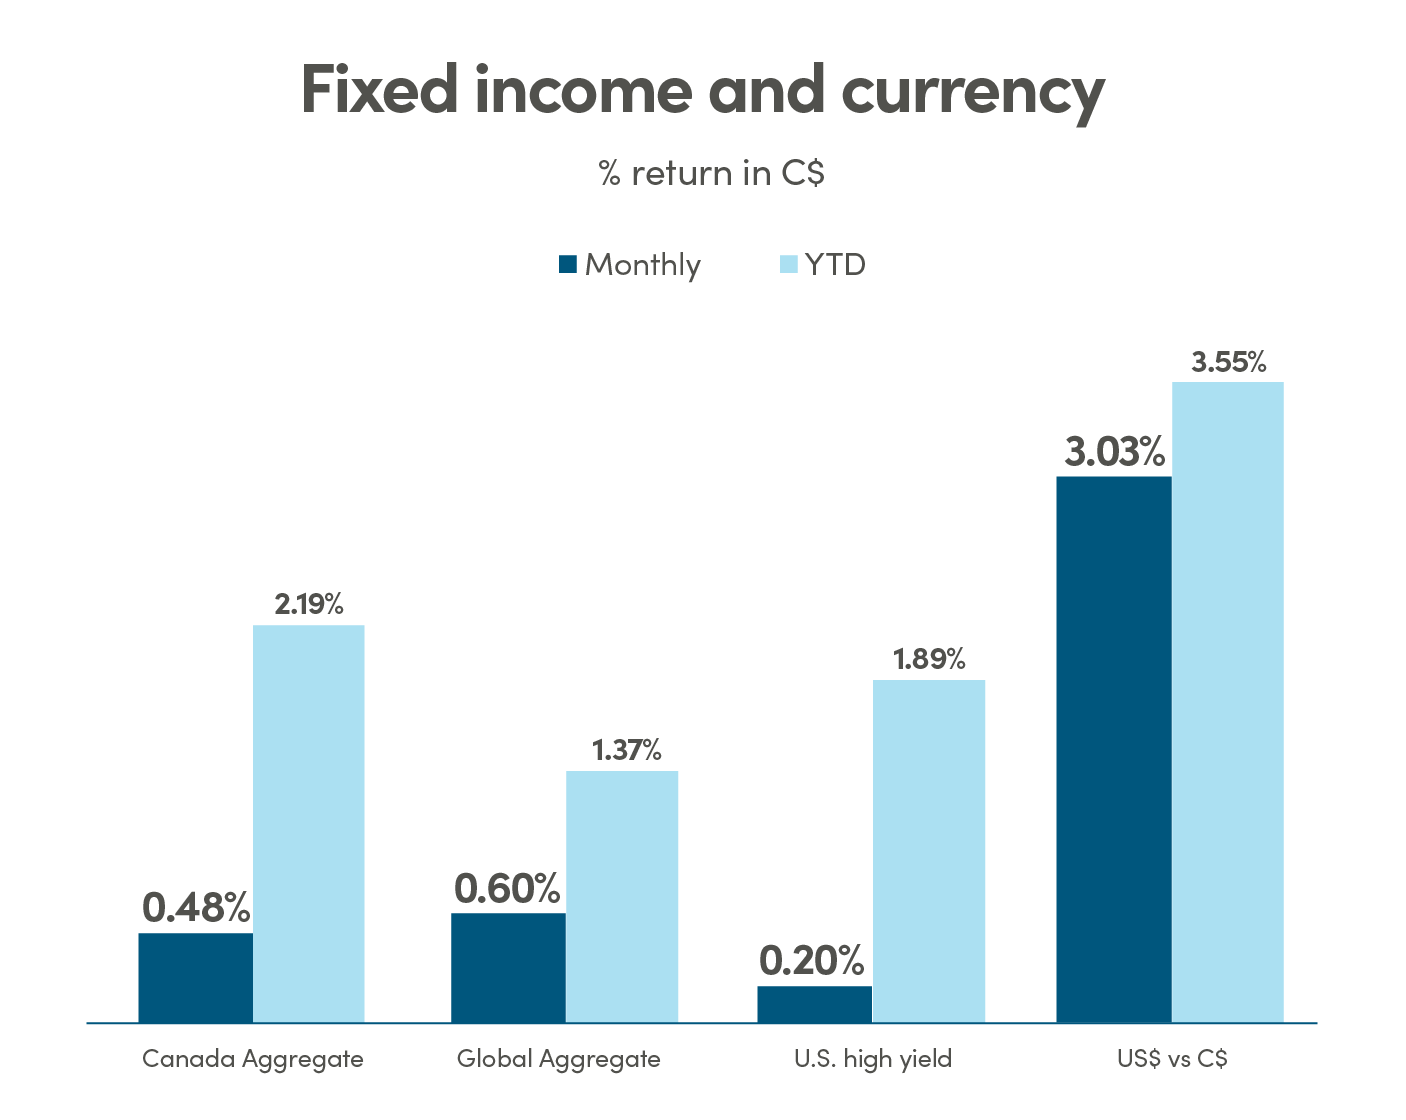
Markets are entering a more complex phase where improving growth signals, moderating inflation, and evolving capital markets dynamics are unfolding simultaneously. While recession risks have eased, the economy remains uneven beneath the surface, and policy is still restrictive. At the same time, a reopening of the IPO window is beginning to reconnect public markets with long-duration growth assets—an important shift after several years where many of the most dynamic companies remained private. For investors, this backdrop reinforces the importance of diversification across both traditional asset classes and emerging sources of return.
NEI Perspectives
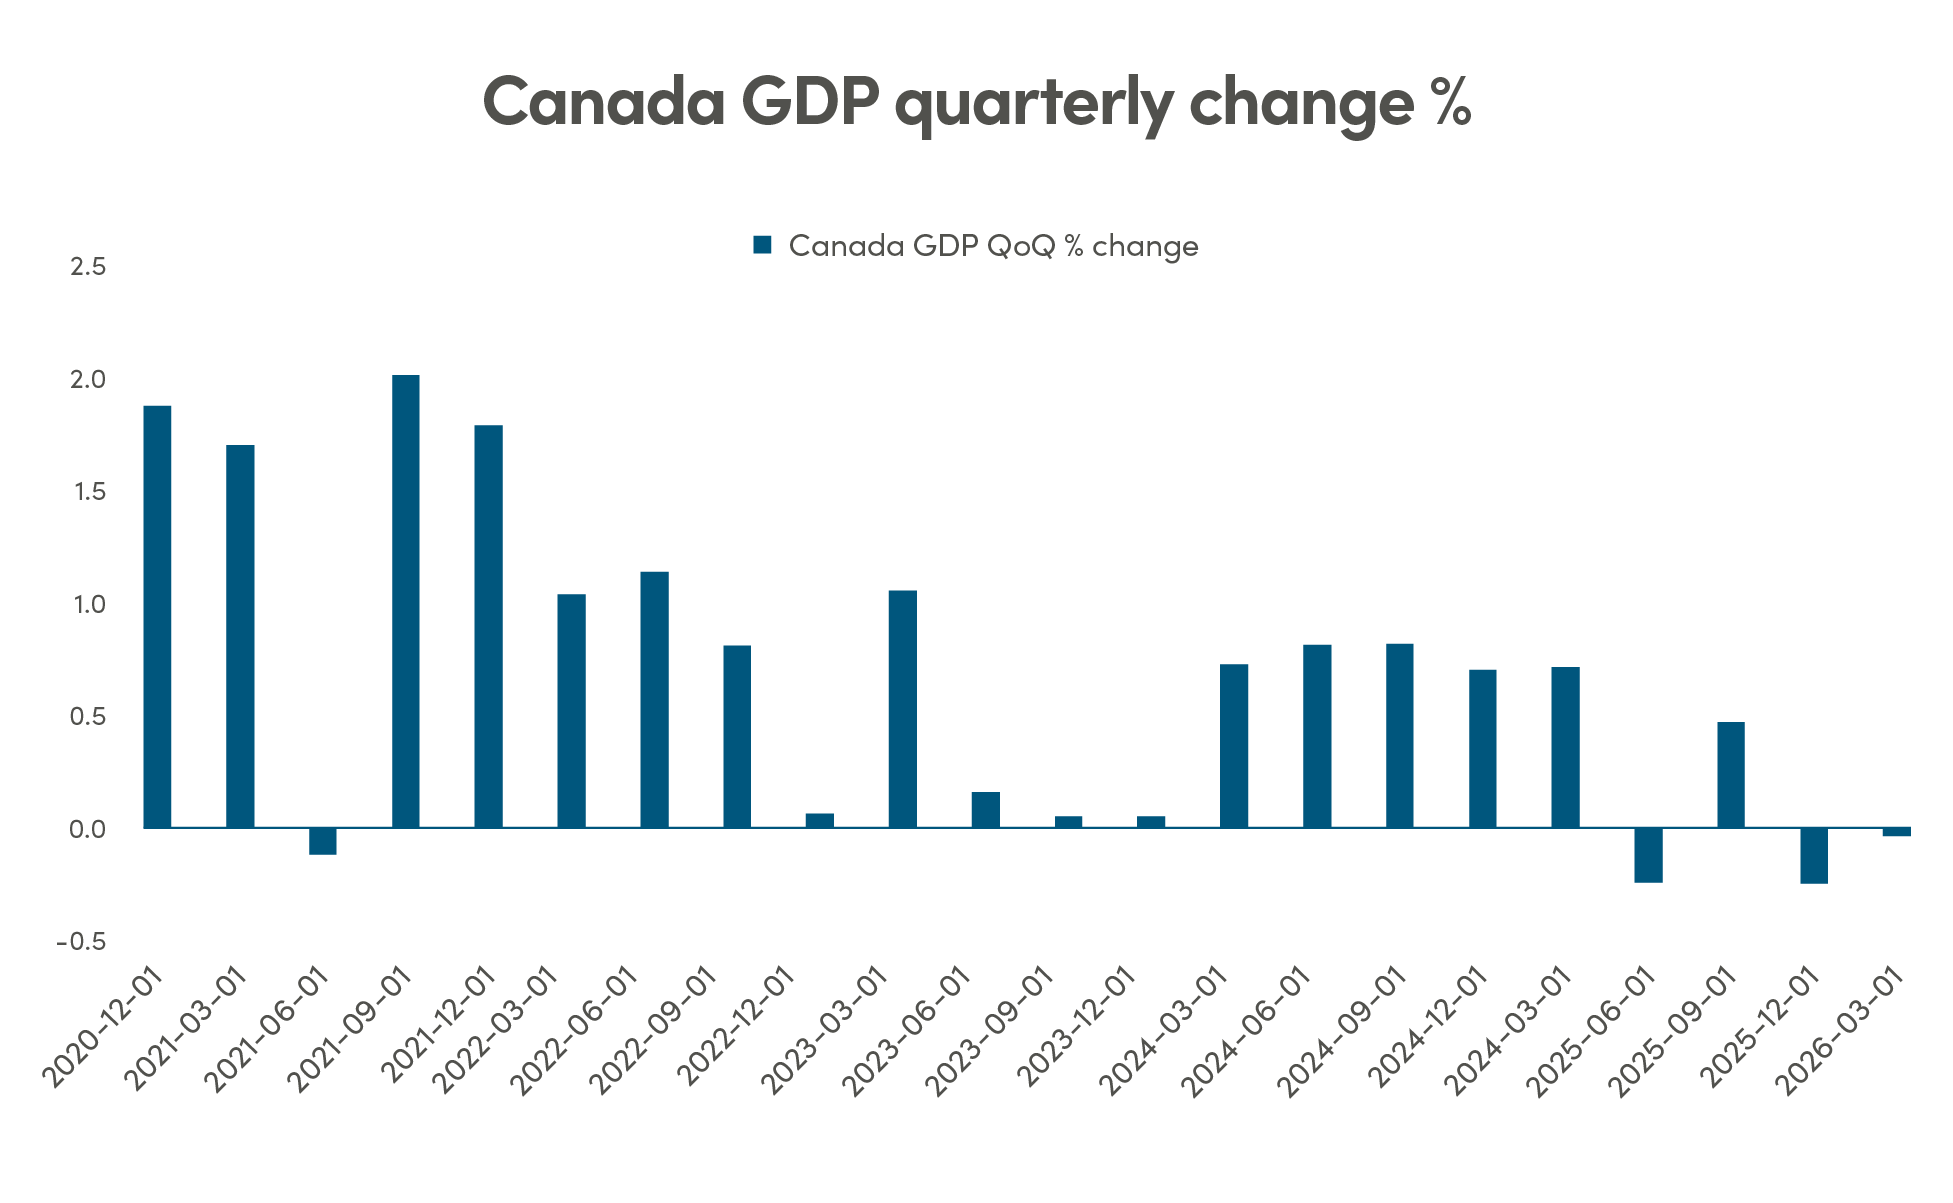
Canadian growth: resilience after a technical recession. Canada’s economy rebounded with a stronger-than-expected GDP print, suggesting underlying stability even as prior weakness reflected the impact of restrictive monetary policy working through the system. Bottom line: Growth is stabilizing but remains uneven and highly rate-sensitive.
IPO market reopening: new pathways to growth exposure. Increasing momentum around high-profile listings highlights a broader reopening of the IPO market after a multi-year slowdown. Bottom line: Early signs of reopening are encouraging, but the IPO market remains sensitive to volatility and valuation conditions.
Disinflation: progress, not completion. Inflation continues to moderate across major economies, but persistent services pressures are keeping central banks cautious about declaring victory. Bottom line: The easing cycle is approaching, but the path will likely be gradual and data-dependent.
- NEI Asset Allocation Team
Source: Bloomberg.
Canada growth: rebound after contraction
Canada’s latest GDP release surprised to the upside following a brief technical recession, pointing to greater underlying resilience in the domestic economy than previously expected. The rebound appears to reflect stabilization across consumer activity and exports, even as higher interest rates continue to weigh on housing, credit-sensitive sectors, and business investment. At the same time, it is too early to conclude that a durable recovery is underway. Much of the prior monetary tightening has yet to fully feed through, and forward-looking indicators remain mixed. The result is likely to be a patchy growth profile, with stronger headline data occasionally masking underlying fragility across rate-sensitive parts of the economy.
Source: Bloomberg.
Bottom line: The economy is proving more resilient than feared, but the cycle remains fragile. Expect continued volatility in growth data as rate effects persist.
IPO market reopening: from private markets to public portfolios
After a prolonged slowdown, the IPO market is beginning to reopen, led by large, high-profile growth companies. This could bring more private-market businesses into public portfolios, but it also raises an important question for investors: at what price?
Many of the companies now coming to market are large, fast-growing, and highly visible, but they are also arriving with elevated valuations, limited trading float, and uneven profitability. That combination can create short-term excitement, particularly when index inclusion forces passive funds to buy, but it can also increase concentration and valuation risk within public markets.
History suggests investors should be careful about treating a reopening IPO window as an automatic positive. Broad baskets of IPOs have generally lagged the market, partly because newly listed companies often share characteristics associated with expected returns such as rich valuations, weaker profitability, and heavy reinvestment needs. The current cycle may be unusual because of the size and profile of the companies involved, but the same discipline applies.
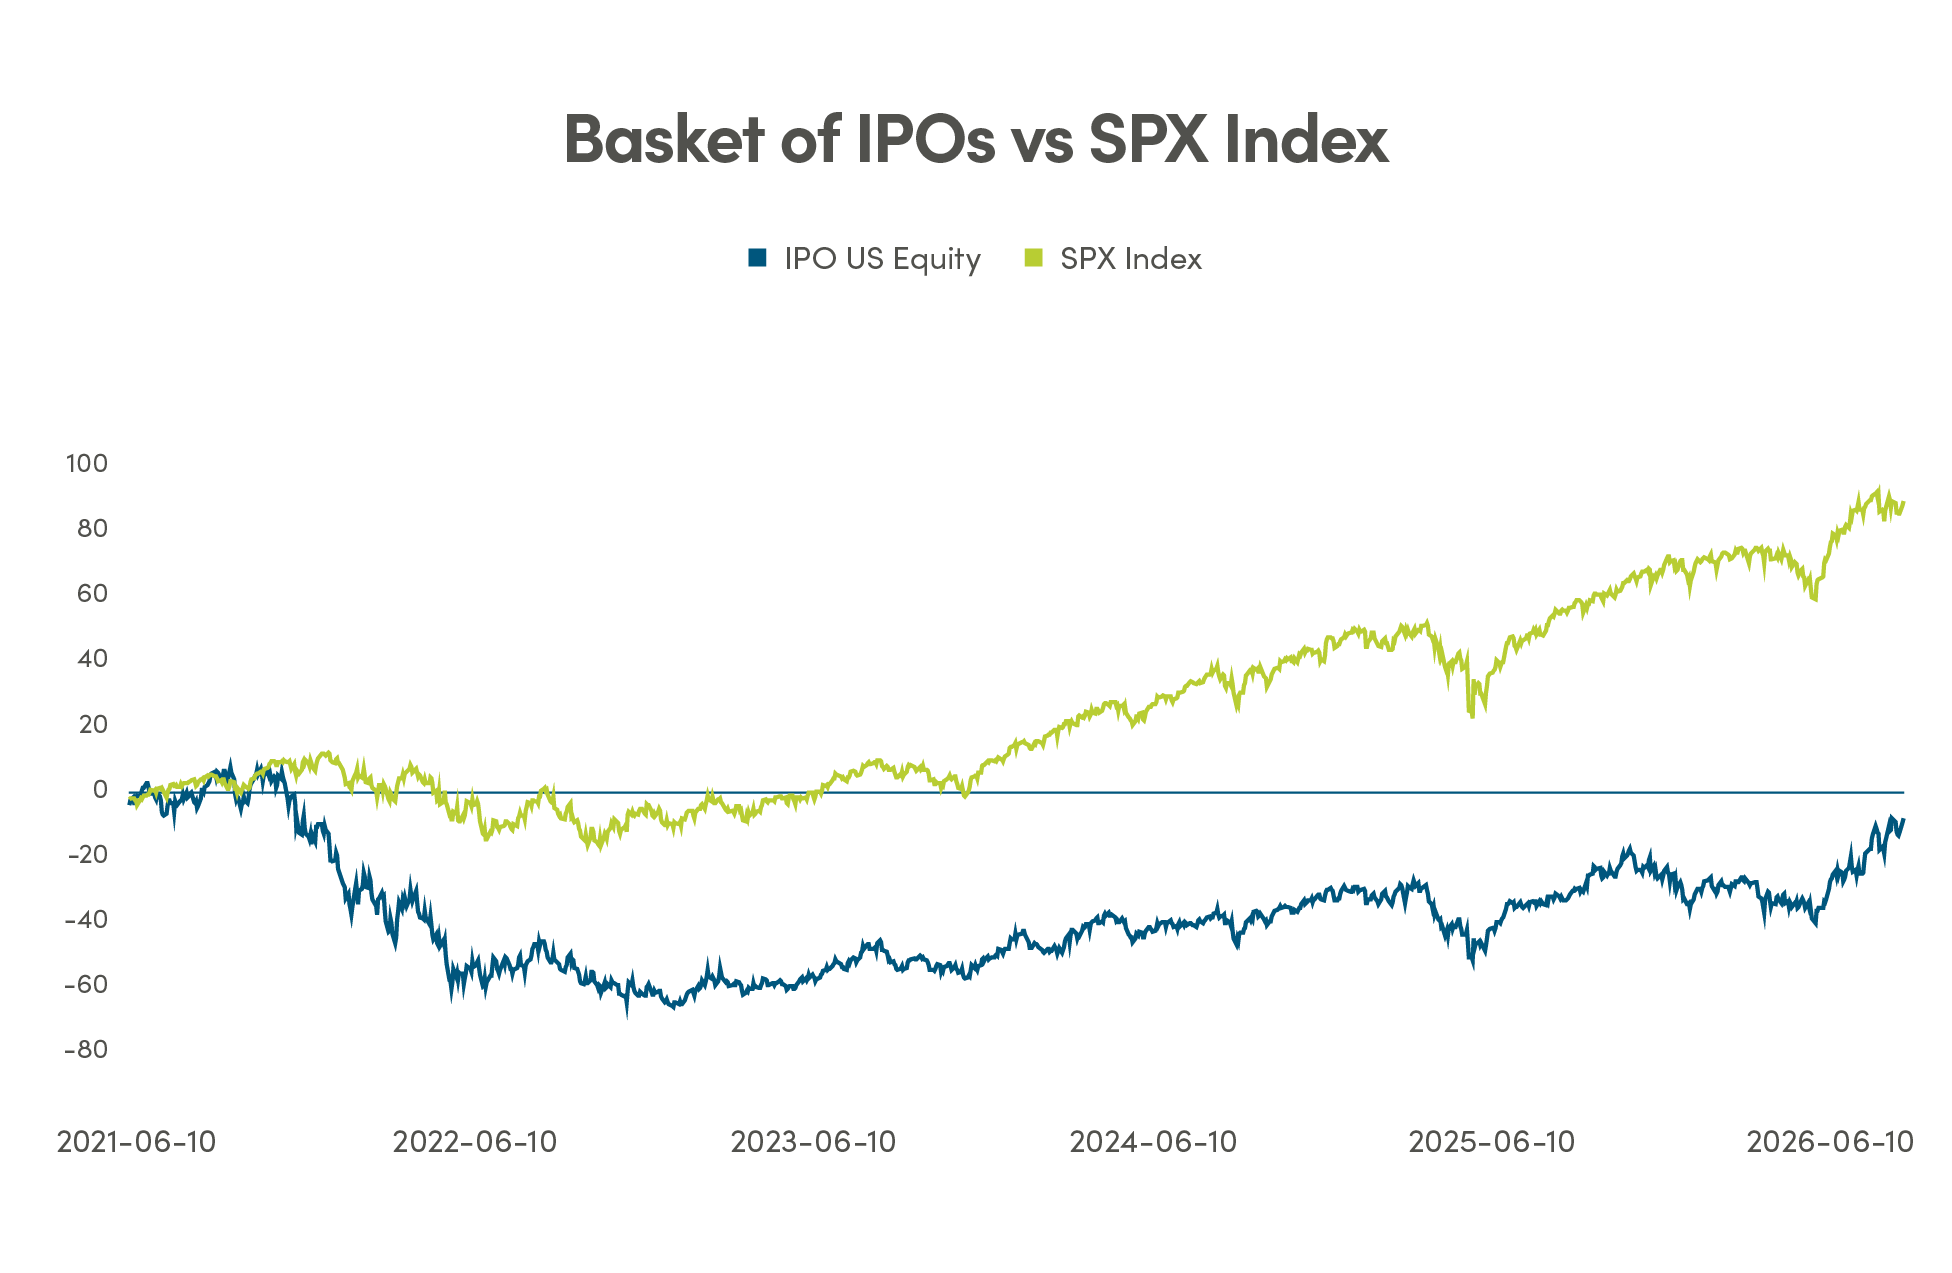
Source: Bloomberg.
Bottom line: A reopened IPO market can expand the public investable universe, but it is not automatically good news. For investors, the key question is whether new listings can justify their valuations once the initial excitement fades and index-driven demand has been absorbed.
Inflation and policy: progress with persistence
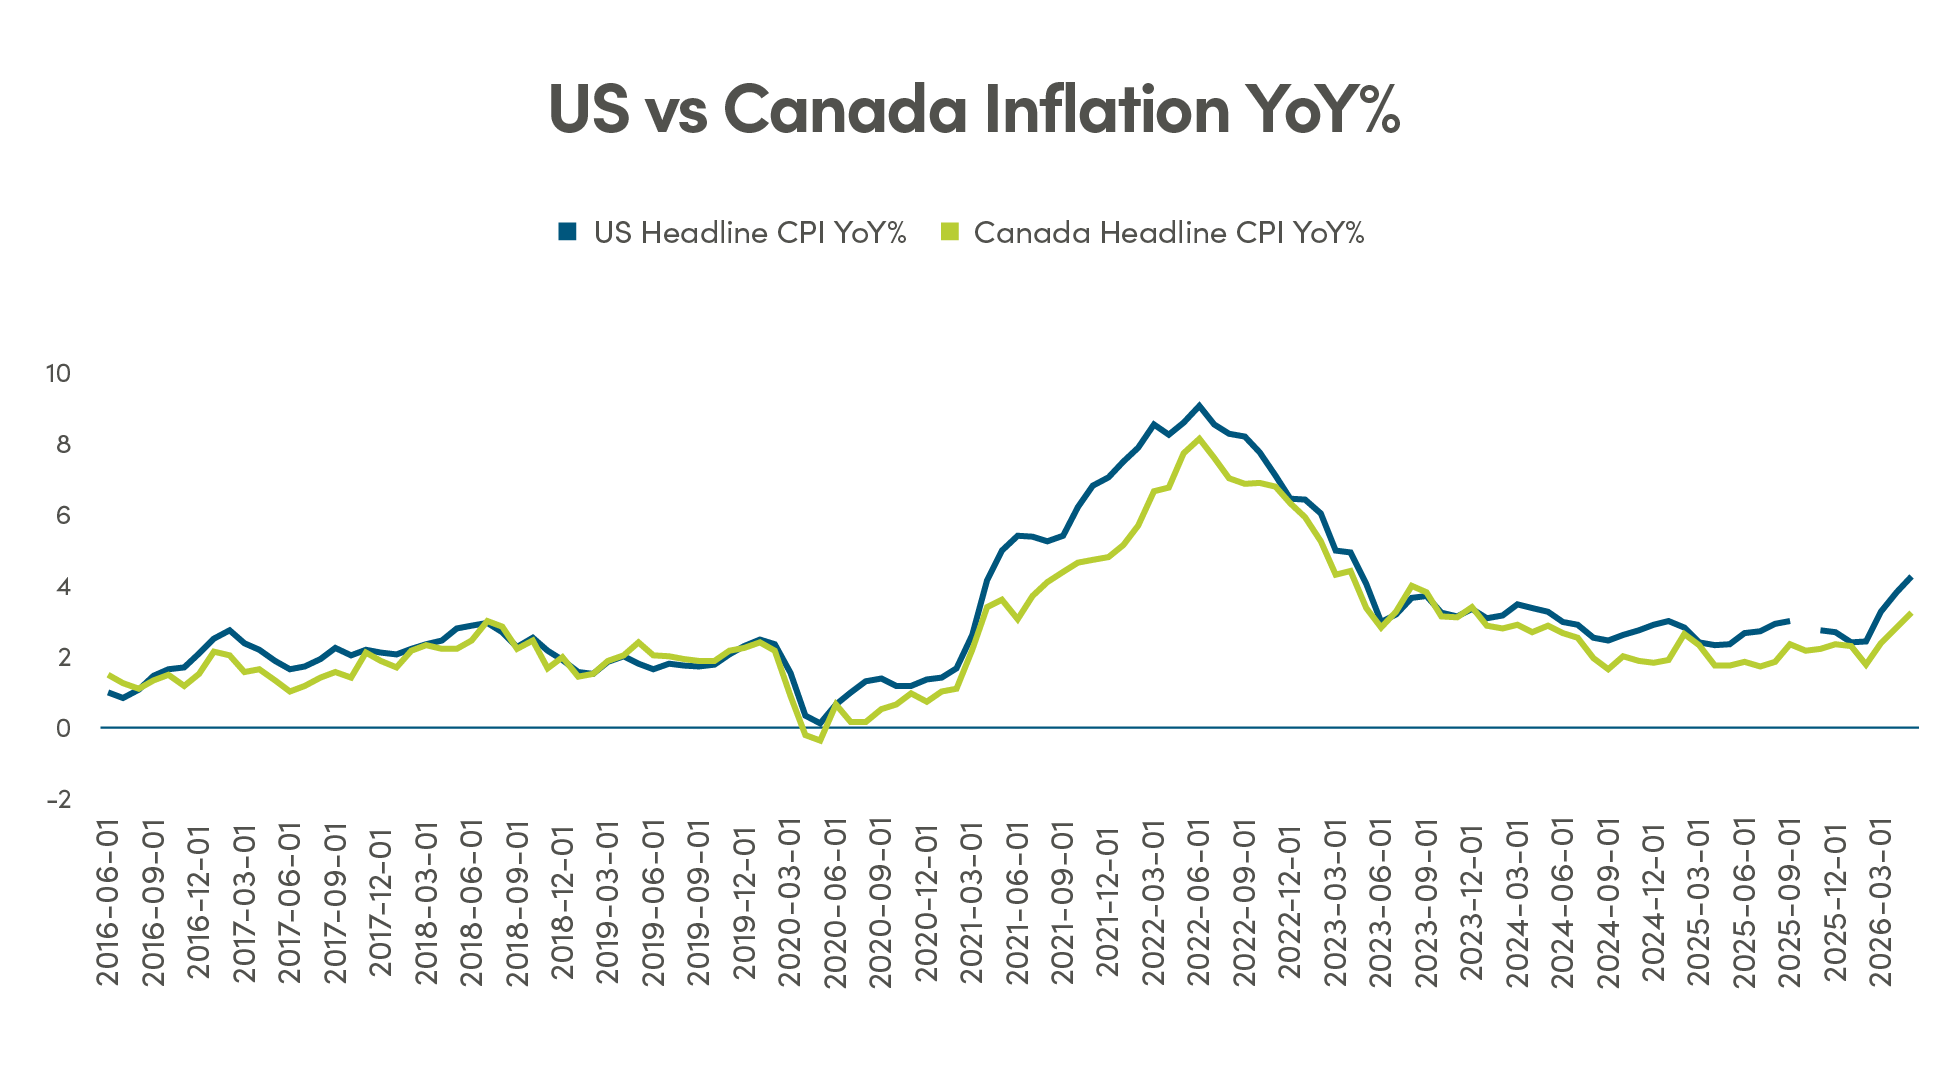
Inflation has continued to move lower across major economies, driven largely by easing goods prices and improvements in global supply chains. However, services inflation remains more persistent, supported by wage dynamics and relatively resilient domestic demand, particularly in developed markets.
This persistence is shaping the central bank response. While policymakers are increasingly confident that inflation is moving in the right direction, they remain cautious about easing too quickly and risking a reacceleration. As a result, markets that have priced in aggressive rate cuts at times may be forced to adjust toward a more gradual and conditional easing path.
For portfolios, this creates a more nuanced rate environment. The direction of travel for policy is likely downward, but the path may be slower and less predictable than in past cycles, particularly if growth remains resilient or inflation proves sticky in key components.
Source: N/A
Bottom line: The direction of rates is likely downward, but timing and magnitude remain uncertain. Position portfolios for a gradual transition rather than a sharp pivot.
Data and opinions as of June 30, 2026.
Aviso Wealth Inc. (“Aviso”) is the parent company of Aviso Financial Inc. (“AFI”) and Northwest & Ethical Investments L.P. (“NEI”). Aviso and Aviso Wealth are registered trademarks owned by Aviso Wealth Inc. NEI Investments is a registered trademark of NEI. Any use by AFI or NEI of an Aviso trade name or trademark is made with the consent and/or license of Aviso Wealth Inc. Aviso is a wholly-owned subsidiary of Aviso Wealth LP, which in turn is owned 50% by Desjardins Financial Holding Inc. and 50% by a limited partnership owned by the five Provincial Credit Union Centrals and The CUMIS Group Limited.
This material is for informational and educational purposes and it is not intended to provide specific advice including, without limitation, investment, financial, tax or similar matters. This document is published by AFI and unless indicated otherwise, all views expressed in this document are those of AFI. The views expressed herein are subject to change without notice as markets change over time. Views expressed regarding a particular industry or market sector should not be considered an indication of trading intent of any funds managed by NEI Investments. Forward-looking statements are not guaranteed of future performance and risks and uncertainties often cause actual results to differ materially from forward-looking information or expectations. Do not place undue reliance on forward-looking information. Mutual funds and other securities are offered through Aviso Financial Inc. Commissions, trailing commissions, management fees and expenses all may be associated with mutual fund investments. Please read the prospectus before investing. Unless otherwise stated, mutual fund securities and cash balances are not insured nor guaranteed, their values change frequently and past performance may not be repeated.
The MSCI information may only be used for your internal use, may not be reproduced or re-disseminated in any form and may not be used as a basis for or a component of any financial instruments or products or indices. None of the MSCI information is intended to constitute investment advice or a recommendation to make (or refrain from making) any kind of investment decision and may not be relied on as such. Historical data and analysis should not be taken as an indication or guarantee of any future performance, analysis, forecast or prediction. The MSCI information is provided on an “as is” basis and the user of this information assumes the entire risk of any use made of this information. MSCI, each of its affiliates and each other person involved in or related to computing, computing or creating any MSCI information (collectively, the “MSCI Parties”) expressly disclaims all warranties (including, without limitation, any warranties of originality, accuracy, completeness, timeliness, non-infringement, merchantability and fitness for a particular purpose) with respect to this information. Without limiting any of the foregoing, in no event shall any MSCI Party have any liability for any direct, indirect, special, incidental, punitive, consequential (including, without limitation, lost profits) or any other damages.
©2026 Morningstar. All Rights Reserved. The information contained herein: (1) is proprietary to Morningstar Research Services LLC, Morningstar, Inc. and/or their content providers; (2) may not be copied or distributed; and (3) is not warranted to be accurate, complete or timely. Neither Morningstar Research Services, Morningstar nor their content providers are responsible for any damages or losses arising from any use of this information. Access to or use of the information contained herein does not establish an advisory or fiduciary relationship with Morningstar Research Services, Morningstar, Inc. or their content providers. Past performance is no guarantee of future results.